RV Loans Explained: Rates, Terms, and How to Get a Better Deal
RV loans make ownership possible for many travelers, but they also shape what the RV really costs you. The monthly payment on the sales sheet tells only part of the story. RV loan rates, fees, term length and depreciation all affect the total you pay and what you owe years from now. This guide explains how RV loans work, what drives RV loan rates, and how to compare offers using official consumer guidance, so you can finance with your eyes open. It is educational, not financial advice.
Last reviewed and updated: September 30, 2026. Written by Jeremy Jarvis.
Key takeaways
- Compare RV loans by APR, which includes the interest rate plus lender fees, not by the monthly payment.
- Longer terms lower the payment but usually raise total interest and the risk of owing more than the RV is worth.
- Get an out-the-door price in writing and a pre-approval before you discuss dealer financing.
- RV loan interest may be deductible in some cases if the RV qualifies as a home; ask a tax professional.
How RV loans work
An RV loan is usually a secured installment loan, with the RV itself as collateral. You borrow the purchase price minus your down payment and any trade-in, then repay it in fixed monthly payments over a set term. If you stop paying, the lender can repossess the RV.
RV loans differ from car loans in two important ways. First, the amounts are often larger. Second, the terms are often much longer, because longer terms keep the payment affordable on an expensive RV. However, that length has a cost, which we cover below. Lenders also treat motorhomes, travel trailers and fifth wheels a little differently, and older RVs may qualify for shorter terms or different rates than new ones.
What drives RV loan rates
RV loan rates are not fixed; each lender sets them based on risk and market conditions. The main factors are:
- Your credit history and score. Stronger credit generally earns lower rates.
- Loan amount and term. Rates can differ for larger loans and for longer terms.
- Down payment. A bigger down payment lowers the lender’s risk.
- RV age and type. Used and older RVs may carry different rates.
- Your debt-to-income ratio. Lenders look at how much of your income already goes to debt.
- The lender itself. Banks, credit unions, online lenders and dealer-arranged financing can all quote differently for the same buyer.
Because RV loan rates change often and depend on your profile, we do not quote numbers here. Instead, gather real quotes and compare them the right way.
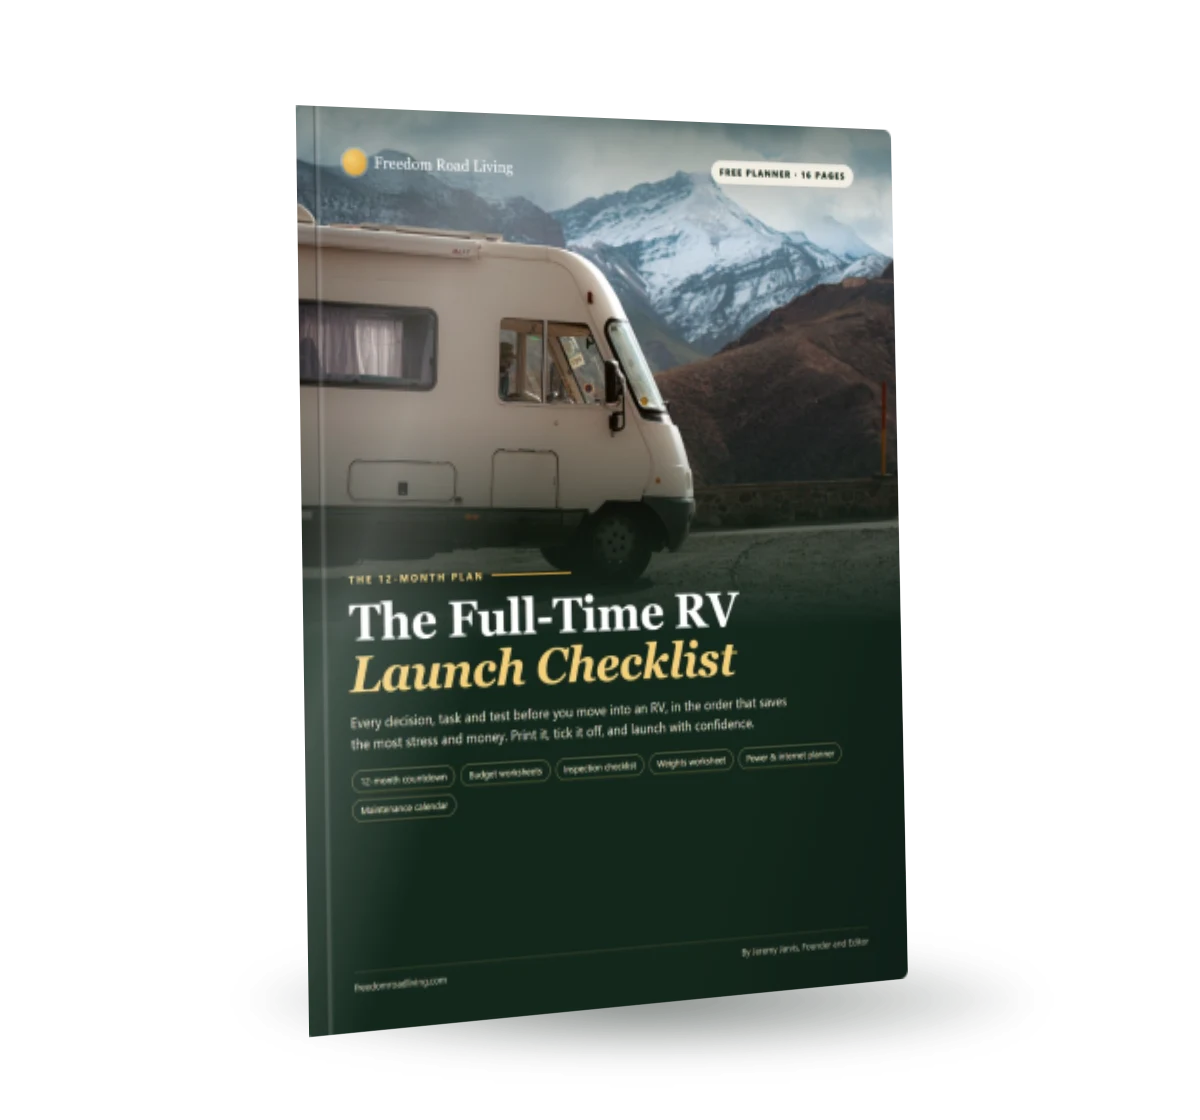
Free download: The Full-Time RV Launch Checklist
Our 16-page planner: a 12-month countdown, inspection checklist, budget and weights worksheets and a maintenance calendar. Free and printable.
APR vs interest rate: compare RV loans the right way
This is the single most useful concept when comparing RV loans. The Consumer Financial Protection Bureau explains that a loan’s interest rate is the cost you pay the lender for borrowing money, while the annual percentage rate (APR) is a measure of the interest rate plus the additional fees charged with the loan. The CFPB also notes that the federal Truth in Lending Act requires lenders to disclose the APR, which means you can use it to compare loans. Just be sure to compare APR to APR, not APR to an interest rate.
In addition, the CFPB points out that dealers and lenders are not required to offer you the best available rates, and that the best way to reduce your costs is to shop around and compare rates between lenders. So treat the first offer as a starting point, not the final word.
Loan terms, payments and total cost
A longer term lowers the monthly payment, which is why long RV loans are common. However, the Federal Trade Commission warns that lower monthly payments often require longer terms and higher interest rates, which can substantially increase your overall cost. In other words, the cheapest-looking payment can be the most expensive loan.
To see the trade-off for yourself, enter the same RV price into our RV Loan Payment Calculator at two or three different terms. Compare the monthly payment with the total interest. Most buyers are surprised by how much the total rises with each extra year. Then, to work out a sensible price range from your budget, use the RV Purchase Affordability Calculator, which reserves room for insurance, storage and maintenance before it sizes the loan.
Worked example: how the term changes the total cost of RV loans
To show why term length matters, here is an illustrative example using the standard amortization formula, the same one our loan calculator uses. It assumes $60,000 financed at an example APR of 8 percent. That rate is for illustration only and is not a quote; your own RV loan rates will differ.
| Term | Monthly payment | Total of payments | Total interest |
|---|---|---|---|
| 10 years (120 months) | About $728 | About $87,360 | About $27,360 |
| 15 years (180 months) | About $573 | About $103,210 | About $43,210 |
| 20 years (240 months) | About $502 | About $120,450 | About $60,450 |
In this example, stretching the loan from 10 to 20 years cuts the payment by about $226 a month, but it more than doubles the total interest. Put another way, the 20-year borrower pays roughly as much in interest as the amount they borrowed. Meanwhile, the RV keeps losing value, so the longer loan also raises the risk of negative equity. Run your own numbers in the RV Loan Payment Calculator to see the trade-off for your price and rate.
Comparing RV financing sources
| Source | Strengths | Watch for |
|---|---|---|
| Credit unions | Often member-friendly terms and personal service | Membership requirements and RV age limits |
| Banks | Existing relationship, easy pre-approval for customers | Stricter criteria for older or larger RVs |
| Online and specialty lenders | Experience with RV loans and fast quotes | Fees that raise the APR above the rate |
| Dealer-arranged financing | Convenience at the point of sale | Rate markups and add-ons rolled into the loan |
No single source is always cheapest. Therefore, the most reliable way to get better RV loan rates is to collect several written offers and compare them by APR and total cost.
Depreciation and negative equity
RVs usually lose value, and often fastest in the first years. Meanwhile, a long loan pays down principal slowly at first. The combination can leave you owing more than the RV is worth, which the FTC calls negative equity. Negative equity is a problem if you want to sell or trade in early, or if the RV is totaled and insurance pays less than the loan balance.
There are several ways to reduce the risk. For example, make a larger down payment, choose a shorter term if the payment still fits, or consider a gently used RV that has already taken its steepest depreciation. In addition, ask your insurer about coverage options that address the gap between the RV’s value and your loan balance.
Where to get RV financing
You have several options, and comparing them is the best way to get a better deal.
- Banks and credit unions: many offer RV loans, and credit unions sometimes have competitive rates for members.
- Online and specialty lenders: some focus on RV and recreational loans.
- Dealer-arranged financing: convenient, and sometimes competitive, but compare it with outside offers.
Getting pre-approved by a bank, credit union or online lender before you visit a dealer gives you a benchmark. If the dealer beats it, great; if not, you already have financing ready.
How to get a better RV loan, step by step
- Check your credit report first. The FTC recommends getting a copy of your credit report before you visit a dealership, so you can fix errors in advance.
- Set your budget. Decide what you can comfortably pay each month, including insurance, storage and maintenance, not just the loan.
- Save for a down payment. The FTC notes that a down payment reduces the amount you need to finance.
- Get pre-approved. Collect quotes from two or three lenders and compare APRs.
- Get an out-the-door price in writing. The FTC advises getting the total price, including taxes and fees, before discussing financing, so you can compare offers and catch add-ons.
- Negotiate. The CFPB notes that you can negotiate the terms of an auto loan, and the same principle applies to RV financing.
- Read every disclosure. Check the APR, term, total of payments, prepayment rules and any add-ons before you sign.
Credit and qualifying for RV loans
Lenders look at your whole financial picture, not just one number. Your credit history shows how you have handled debt. Your income and existing debts show whether a new payment fits. As a result, two buyers with similar credit scores can receive different offers. To strengthen your application, pay down other balances where you can, avoid opening new credit right before you apply, and fix any errors on your credit report first. In addition, a larger down payment can improve the terms you are offered, because the lender takes less risk.
Refinancing and paying off RV loans early
RV loan rates change over time, and so does your credit. Consequently, some owners refinance later to lower their rate or shorten their term. Before refinancing, compare the new APR, any fees, and the total cost over the remaining term, because a lower payment over a longer period can cost more overall.
Paying extra toward principal is another way to cut total interest and build equity faster. However, check your loan agreement for any prepayment penalty first. Then, if there is none, even small extra payments early in the loan can make a noticeable difference, because interest is calculated on the remaining balance.
Watch out for add-ons
At signing, you may be offered extended service contracts, gap coverage, paint and fabric protection, and other extras. Some can be useful, but they can also add a lot to the amount you finance, and you pay interest on them for the life of the loan. So ask for each add-on’s price separately, decide whether you want it, and remember that you can usually decline them or buy some from other sources.
Taxes and RV loan interest
Some RV owners may be able to deduct RV loan interest. IRS Publication 936 explains that a home for the mortgage interest deduction includes a house, condominium, mobile home, house trailer, boat or similar property that has sleeping, cooking and toilet facilities. Therefore, an RV with those facilities may qualify as a main or second home in some circumstances. However, the rules on secured debt, itemizing and limits are specific, so ask a qualified tax professional before counting on a deduction.
Should you finance, pay cash or rent?
Financing spreads the cost, but it adds interest. Paying cash avoids interest but ties up savings you might need for repairs or emergencies. Renting avoids both, and it can be cheaper if you travel only a few weeks a year. Before you commit, compare owning and renting with our RV Rental vs. Purchase Calculator, which includes depreciation. And if you are new to RVing, our guide on how to rent an RV explains how to test the lifestyle before you buy.
RV loans checklist
- Credit report checked and errors fixed.
- Monthly budget set, including running costs.
- Down payment saved.
- Two or three pre-approval quotes compared by APR.
- Out-the-door price in writing.
- Loan term chosen with total interest in mind.
- Add-ons reviewed and priced separately.
- RV inspected before signing, using our New RV Inspection Checklist.
A little preparation turns RV loans from a sales-floor decision into a planned one. For more guidance on the costs of life on the road, see our RV Living hub.
Frequently asked questions about RV loans
What is the difference between an RV loan’s interest rate and its APR?
The CFPB explains that the interest rate is the cost you pay the lender for borrowing, while the APR is the interest rate plus additional fees charged with the loan. Because lenders must disclose the APR, it is the better number for comparing offers.
How long can you finance an RV?
RV loans often run much longer than car loans, and terms vary by lender, loan amount and RV age. Longer terms lower the monthly payment but usually increase the total interest you pay.
Is it better to finance an RV through a dealer or a bank?
Compare both. The CFPB notes that dealers and lenders are not required to offer you the best available rates, so shopping around with banks, credit unions and online lenders, and bringing a pre-approval to the dealer, puts you in a stronger position.
Is RV loan interest tax deductible?
It can be in some cases. IRS Publication 936 says a home can include a mobile home, house trailer, boat or similar property that has sleeping, cooking and toilet facilities. Whether you qualify depends on your situation, so ask a tax professional.
What is negative equity on an RV loan?
Negative equity means you owe more than the RV is worth. It is common with long loans and small down payments because RVs usually lose value quickly. A larger down payment and a shorter term reduce the risk.
Sources and how we researched this guide
This guide is educational and research-based, not financial advice. Guidance on APR, loan disclosures and dealer financing comes from the Consumer Financial Protection Bureau and the Federal Trade Commission, and the tax point comes from IRS Publication 936. We do not quote specific rates, because they change daily and depend on your credit and the lender. Found something out of date? Tell us and we will check it against the source.
- CFPB: interest rate vs APR
- CFPB: auto loan tools and guidance
- FTC: financing or leasing a car
- IRS Publication 936: home mortgage interest deduction
Keep planning
- New vs Used RV: Which Should You Actually Buy?
- Cost of Full-Time RVing: A Realistic Monthly Budget, Line by Line
- Full-Time RV Living: A Complete Guide to Planning, Costs and Life on the Road
- RV Domicile and Mail Forwarding: How Full-Time RVers Choose a Home State
Go deeper: RV Living hub · RV Purchase Affordability Calculator · RV Loan Payment Calculator · New RV Inspection Checklist
Written by Jeremy Jarvis
Jeremy Jarvis is the founder and editor of Freedom Road Living, where he builds research-based guides and free planning tools for people who live, work and travel in an RV. He sets the site's editorial standards, checks every guide against official sources such as the National Park Service and manufacturer documentation, and is responsible for corrections. Jeremy also founded Eco Nomad Travel, Mind Clarity Hub, SilkHarborTravel and WanderOza Travel, and he is the author of books on clarity, focus and practical AI, including The Power of Clarity and Digital Clarity.